- | 3:45 pm
Banks could take biggest share of new UPI fee profits
India’s new merchant fee regime could generate ₹27,000 crore in annual revenue by fiscal 2028, with banks capturing most of the resulting profits, estimates show
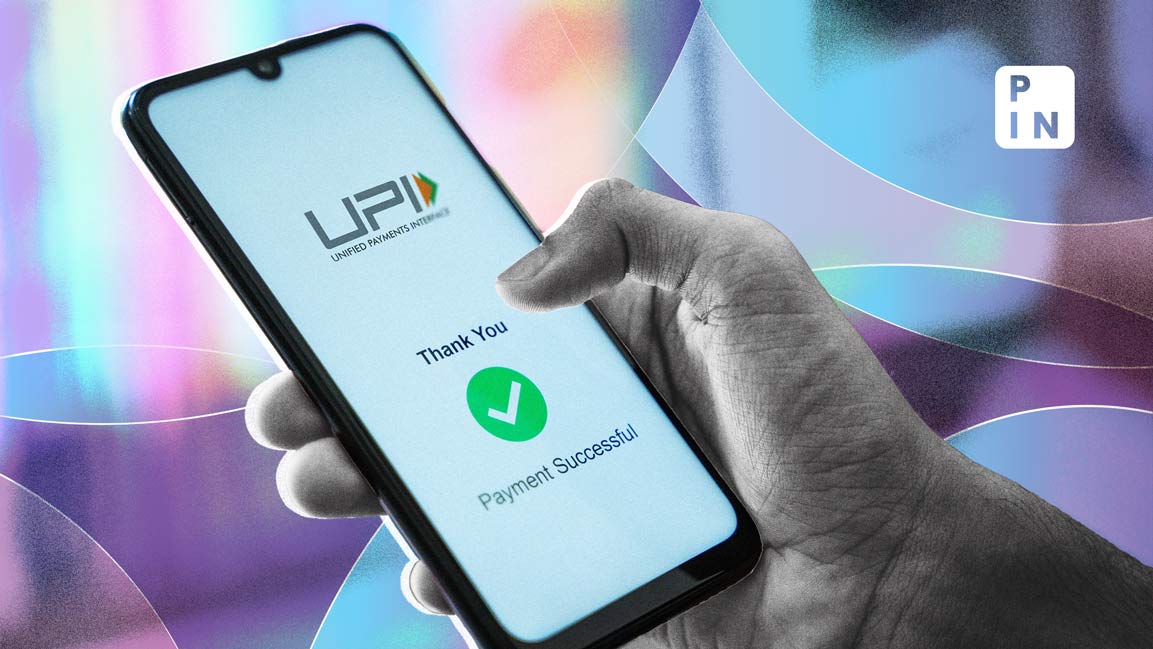


Indian banks could emerge as the biggest financial beneficiaries of India’s new fees on higher-value UPI merchant payments, with Bernstein estimates reported by The Economic Times putting the potential annual revenue pool at about ₹27,000 crore ($2.8 billion) by fiscal 2028.
The payments ecosystem could earn nearly ₹20,000 crore ($2.1 billion) in profit from the fees, with banks retaining about 60%, or ₹12,000 crore ($1.25 billion), Bloomberg reported, citing a Bernstein research note by analysts including Pranav Gundlapalle.
State Bank of India could be among the biggest beneficiaries because of its share of bank accounts used to originate UPI payments. Axis Bank and YES Bank could also gain because they process a disproportionately large share of UPI transactions relative to their broader banking market shares, according to Bernstein estimates cited by Bloomberg.
The three banks also outperformed the broader banking index on Thursday. Shares of SBI rose about 2.4%, those of Axis Bank by 1.5% and YES Bank 1.4%, while the Nifty Bank index was up only about 0.1%.
India’s finance ministry said on 15 September that a merchant discount rate, or MDR, of 0.4% will apply to specified person-to-merchant UPI transactions above ₹2,000 under the new framework.
The charge will be capped at ₹300 on transactions of ₹75,000 or more. Payments above ₹2,000 in sectors including railways, telecommunications, insurance, fuel and agricultural inputs will instead face a flat ₹5 MDR. Capital-market payments will attract an MDR of 0.02%, capped at ₹300.
Consumers will not pay the MDR. The government has also advised banks to ensure merchants do not pass the charge on to customers, while UPI application providers are prohibited from imposing platform fees or hidden charges.
Person-to-person UPI transactions will remain free regardless of value, as will merchant payments of up to ₹2,000. Small merchants receiving up to ₹1 lakh a month through qualifying UPI QR-code payments will also continue to pay zero MDR.
The transactions that become chargeable, however, account for a much larger share of payment value. Transactions above ₹2,000 represented about 4% of merchant-payment volume in August but 67% of the value, Bloomberg reported, citing NPCI data.
Bernstein estimates reported by ET put UPI person-to-merchant transaction value at about ₹144 trillion ($1.5 trillion) by fiscal 2028. After exemptions and lower rates for some categories, the brokerage estimates an effective MDR of about 0.19% across total merchant-payment value.
Bernstein’s projected ₹27,000 crore revenue pool includes about ₹10,800 crore for issuing banks, ₹5,400 crore to consumer-facing UPI applications and ₹2,700 crore to payment-service-provider banks partnered with those apps.
Merchant-side payment applications could receive another ₹5,400 crore to ₹6,800 crore, while beneficiary or acquiring banks could receive about ₹1,400 crore to ₹2,700 crore, according to the Bernstein estimates reported by ET.
Bernstein estimates the new fee regime could lift banking-system profits by about 3%, Bloomberg reported, although the gains are expected to be uneven.
An amount equivalent to 5% of total MDR collections will also be contributed to a dedicated fund intended to expand UPI adoption among small merchants.
The framework gives banks and payment companies a direct revenue source after several years of zero MDR on UPI merchant payments. Industry participants have argued that surging UPI volumes have increased spending on infrastructure, cybersecurity, fraud prevention and customer service.
More Top Stories: